Mortgage Rates in Redondo Beach, CA: What Buyers and Sellers Need to Know
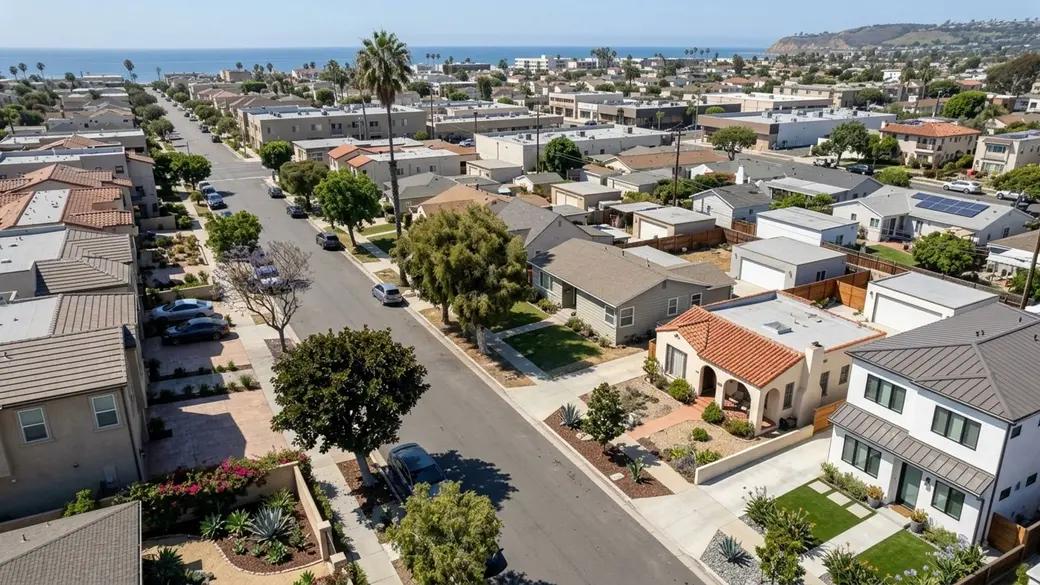
The median sale price of a home in Redondo Beach, CA is currently around $1.57 million. At that price point, your interest rate shapes your monthly housing costs just as much as the purchase price itself, especially for first-time home buyers in Redondo Beach.
Whether you're buying your first townhome in South Redondo or selling a property near the Pier, financing costs run through every part of this market. Knowing how loans are priced - and how to find the right local lender - is how you make a sound decision instead of an expensive guess.
How Mortgage Rates Work Today in Redondo Beach, CA
Interest rates move constantly throughout the trading day based on bond markets, inflation data, and Federal Reserve policies. Because those broader economic factors shift by the minute, lenders update their pricing daily or even multiple times a day.
You'll see plenty of advertised rates online. Those numbers almost always assume an idealized borrower with a massive down payment and flawless credit. The only rate that matters is the one a lender offers you specifically.
Where to Find Your Actual Rate
To see what loan costs apply to your situation, get a direct quote from a lender. When you apply, the lender provides a standardized document called a Loan Estimate.
That document breaks down the exact interest rate, annual percentage rate (APR), and estimated closing costs based on your specific financial profile. Comparing Loan Estimates from different lenders is the most accurate way to see who's offering the best terms.
Why Daily Rate Changes Happen
Mortgage pricing is tied closely to the yield on 10-year Treasury bonds. When investors demand higher returns on those bonds - because of inflation or economic shifts - the cost to borrow money for a house goes up right along with it.
Lenders also adjust daily pricing based on their own internal capacity. If a bank has more applications than it can process, it might nudge rates higher to slow down new business. It's not personal. It's pipeline management.
What the Rate Means for Your Buying Power in the South Bay
A small shift in interest changes your monthly obligation when you're purchasing real estate in Los Angeles County. Your budget calculation needs to start with the complete monthly payment - not just the home's sticker price.
With the median home price in Redondo Beach sitting near $1.57 million, most buyers are financing well over a million dollars. At those loan amounts, even a half-percent difference moves the monthly payment by hundreds of dollars. That's a real number, not a rounding error.
Monthly Payment Comparisons for a Redondo Beach Home
Consider a buyer putting 20% down on a $1,570,000 home, resulting in a $1,256,000 loan. If the rate is 6%, the principal and interest payment runs roughly $7,530 per month. At 6.5%, that same loan costs about $7,938 per month. At 7%, the payment climbs to roughly $8,356.
A 1% jump in the rate adds more than $800 to the monthly cost - before taxes and insurance.
The Trade-Off Between Home Price and Interest Rate
Buyers often wrestle with whether to wait for a lower rate or negotiate harder on the purchase price. When borrowing costs are higher, buyer demand tends to cool, which can lead to homes sitting on the market a bit longer. Right now, homes in Redondo Beach spend an average of 44 days on the market.
Buyers who purchase during slower demand periods might lock in a better price. And if rates fall later, you can always refinance.
Fixed vs. Adjustable-Rate Mortgages and Other Loan Types
The type of loan you choose directly impacts the interest you pay over time. Lenders offer different products to fit different timelines and financial goals, and your loan will be priced based on how long the rate is guaranteed to stay fixed and whether any government entity is backing it.
Choosing Between 30-Year and 15-Year Fixed Loans
A 30-year fixed loan spreads payments over three decades, keeping the monthly cost as low as possible. The rate is generally higher than on shorter-term loans, but the predictable payment makes it the most popular choice by a wide margin.
A 15-year fixed loan comes with a lower interest rate and lets you pay off the house in half the time. The trade-off is a much higher monthly payment - which gets uncomfortable fast at South Bay price points.
How ARMs Work in Los Angeles County
An adjustable-rate mortgage (ARM) typically offers a lower introductory rate for a set period - five or seven years, for example. After that initial period ends, the rate adjusts annually based on broader market indexes.
ARMs appeal to buyers who know they'll sell or refinance before the fixed period expires. If you're planning to stay in your Redondo Beach home for decades, an ARM carries real risk of higher payments down the road.
Differences Between Conventional, FHA, VA, and USDA Loans
Conventional loans aren't backed by the government and generally require stronger credit scores to get the best pricing. Most buyers in Redondo Beach use conventional or jumbo loans, given the high loan limits in Los Angeles County.
FHA loans are insured by the Federal Housing Administration and allow for lower credit scores, though they require mortgage insurance. VA loans are available to eligible veterans and military members, offering competitive terms with zero down payment required. USDA loans are for rural properties and don't apply to the densely populated South Bay.
How to Get the Best Mortgage Rate as a Buyer
You can't control the bond market. You can control the factors lenders use to evaluate your application. Lenders reward borrowers who present the lowest risk of default, and preparing your finances before you apply for pre-approval gives you real leverage.
How Your Credit Score Affects Your Loan
Your credit score is the single biggest personal factor in determining your loan pricing. Borrowers with scores of 740 or higher generally qualify for the most favorable terms. If your score is in the 600s, you'll pay a meaningful premium for it.
Taking a few months to pay down credit card balances and correct any errors on your credit report can produce significant savings over the life of your loan. It's worth checking before you start the process.
Down Payments, Points, and Buy-Downs
Putting more money down reduces the lender's risk, which often translates to a better rate. Put down at least 20% and you also avoid paying private mortgage insurance (PMI).
You can also pay discount points at closing - one point costs 1% of your loan amount and lowers your interest rate by a set fraction of a percent for the entire term. Or you can ask the seller for a temporary buy-down, which subsidizes your payment for the first one to three years.
Shopping Multiple Lenders and Locking Your Rate
Different lenders have different overhead costs and profit margins, so two lenders will quote different rates to the exact same borrower. Applying with three different companies lets you compare their Loan Estimates side by side - apples to apples.
Once you find a favorable offer and have an accepted contract, you can lock your rate. That lock guarantees your pricing won't change before closing, typically for 30 to 60 days.
Finding the Right Mortgage Lender in Redondo Beach, CA
The company you choose to finance your home affects both your monthly payment and your ability to close on time. In a competitive market, the reputation of your lender matters to the seller reviewing your offer - a pre-approval letter from a known, reliable local institution carries more weight than one from an out-of-state call center.
Local South Bay Lenders vs. National Call Centers
Local lenders understand the nuances of the Los Angeles County housing market - typical closing timelines, local property tax structures, and how South Bay properties are valued. They also have established relationships with local appraisers who know this area.
National call centers operate across multiple time zones and routinely hand your file from one department to another. If a problem surfaces a week before closing, reaching a local loan officer on their direct line is far easier than working through a corporate phone tree. I've seen deals unravel because of exactly that.
Banks, Credit Unions, Brokers, and Direct Lenders
Retail banks and credit unions lend their own money and only offer their own loan products. If you have an existing relationship with a local credit union, they might offer you a relationship discount worth asking about.
Mortgage brokers don't lend their own money - they shop your application across dozens of wholesale lenders to find the best match. Direct lenders fund their own loans but specialize exclusively in mortgages, which often allows for faster processing than traditional banks. None of these is automatically the right answer; it depends on your situation.
What Rate Trends Mean If You Are Selling in Redondo Beach
Sellers need to pay attention to borrowing costs because they directly influence how many buyers can afford the property. When financing gets more expensive, buyers get more sensitive to asking prices and property condition.
Even with fluctuating costs, the Redondo Beach market remains active. Homes are currently selling for about 99.6% of their list price on average - well-prepared properties are still commanding strong offers.
How Rates Shape Buyer Demand
As monthly payments rise, some buyers exit the market entirely while others shift their search toward less expensive neighborhoods. You'll likely see fewer groups at your open houses.
That said, buyers who stay in the market during higher-rate periods tend to be well-qualified and motivated. They've already run the numbers and committed. They're less likely to walk away from a contract than a buyer who's stretching.
Pricing and Timing Your Listing
When borrowing costs are elevated, overpricing is a costly strategy. Buyers have less financial wiggle room, so a property that needs work but is priced like a turnkey home will sit. Reviewing recent comparable sales with your agent is how you set a price that attracts offers.
Right now, there are about 148 homes for sale in Redondo Beach, representing a 2.4-month supply. That still favors sellers - but only those who price correctly from day one.
Thinking of Buying or Selling in Redondo Beach? Get Local Guidance
A real estate transaction requires a clear understanding of both the housing market and the financing landscape. Your agent and your lender should work as a team from the first showing to the closing table - not operate in separate silos.
Talk to a Local Agent First
Before you pull your credit or fill out a single loan application, talk to a local real estate agent. An agent can help you understand what homes cost in your target neighborhoods so you know exactly how much you'll need to borrow.
They can also walk you through current market dynamics - how long homes are taking to sell, and whether sellers are currently offering concessions to help buy down interest rates.
Connecting With a Trusted Local Lender
Agents work with lenders every day and know which ones close on time and communicate clearly. They can introduce you to local professionals with a real track record in Redondo Beach.
Getting pre-approved by a respected local lender also signals to sellers that you're serious and ready to close. That matters more than most buyers realize.
Mortgage Rate FAQs
What are mortgage rates today in Redondo Beach, CA?
Rates change multiple times a day based on the bond market and your specific financial profile. To get an accurate number for today, request a direct quote or a Loan Estimate from a local lender. Advertised rates online rarely reflect the exact terms you'll receive.
How much does a 1% difference in mortgage rate cost me on a South Bay home?
With the median Redondo Beach home priced around $1.57 million, a 1% rate increase on a typical 20%-down loan adds more than $800 to your monthly principal and interest payment. That shift changes the total budget required to afford a home in the area.
How do I get the best mortgage rate as a buyer in Redondo Beach?
You secure the best terms by maintaining a credit score of 740 or higher and saving for a larger down payment. Apply with at least three different lenders and compare their Loan Estimates side by side.
Should I wait for rates to drop before buying a home in Redondo Beach?
It depends on your timeline and budget. Waiting for costs to fall can backfire - lower borrowing costs often bring more buyers into the market, which drives up home prices. If you find a home that fits your budget now, you always have the option to refinance if rates drop later.
How do I choose a local mortgage lender in Redondo Beach, CA?
Look for a lender with a strong reputation for closing on time and communicating clearly with local agents. Ask your real estate agent for introductions to trusted local professionals, then compare the Loan Estimates they provide to see who offers the lowest overall costs.
Will current mortgage rates make it harder to sell my home in Redondo Beach right now?
Not if your home is priced correctly. Higher borrowing costs do reduce the overall number of buyers, but homes in Redondo Beach are currently selling for about 99.6% of their list price - well-priced properties still attract serious offers.
Do I need a jumbo loan to buy in Redondo Beach, and how will that impact my interest rate?
In many cases, yes. Because the median sale price is around $1.57 million, many buyers in the area require a jumbo loan to finance their purchase. Jumbo loans have tighter credit requirements than conforming loans, but they sometimes offer slightly lower interest rates depending on the lender's portfolio.
Are closing fees included in my mortgage rate quote?
Your lender will provide a Loan Estimate that breaks down your exact interest rate alongside your estimated closing costs. Reviewing this standardized document is the most accurate way to understand your buyer closing costs in Redondo Beach before finalizing your loan.
How do interest rates affect my property budget in the South Bay?
A small shift in your interest rate changes your monthly obligation, which directly impacts your home affordability in Redondo Beach. Your budget calculation needs to start with the complete monthly payment rather than just looking at the sticker price.
Categories
Recent Posts